Market Entry Strategy for Protein Snacks: From First Store to Wider Distribution
Kort sammanfattat
A protein snack market entry works best as a staged rollout: prove demand and repeat purchase in one or a few well-chosen stores, read the sell-through data honestly, then use that evidence to scale into regional wholesale, national listings or a private-label programme rather than chasing wide distribution first.
TL;DR
- Win a protein snack market entry by proving velocity in a first store, then scaling to wider distribution on the strength of real sell-through data.
A successful protein snack market entry is a staged process, not a launch event. The most dependable path runs from a small, well-chosen store trial to regional wholesale and, eventually, national listings or a private-label programme — with each stage funded by evidence from the one before it. For a retail buyer or distributor, the smartest way to de-risk a new protein snack is to treat the first store not as a sale to celebrate but as a controlled experiment that produces the sell-through data every later decision depends on.
A protein snack earns wider distribution by proving velocity in a handful of stores first. Data from a disciplined pilot — not a persuasive pitch deck — is what unlocks the next tier of shelves.
What protein snack market entry really means for a buyer
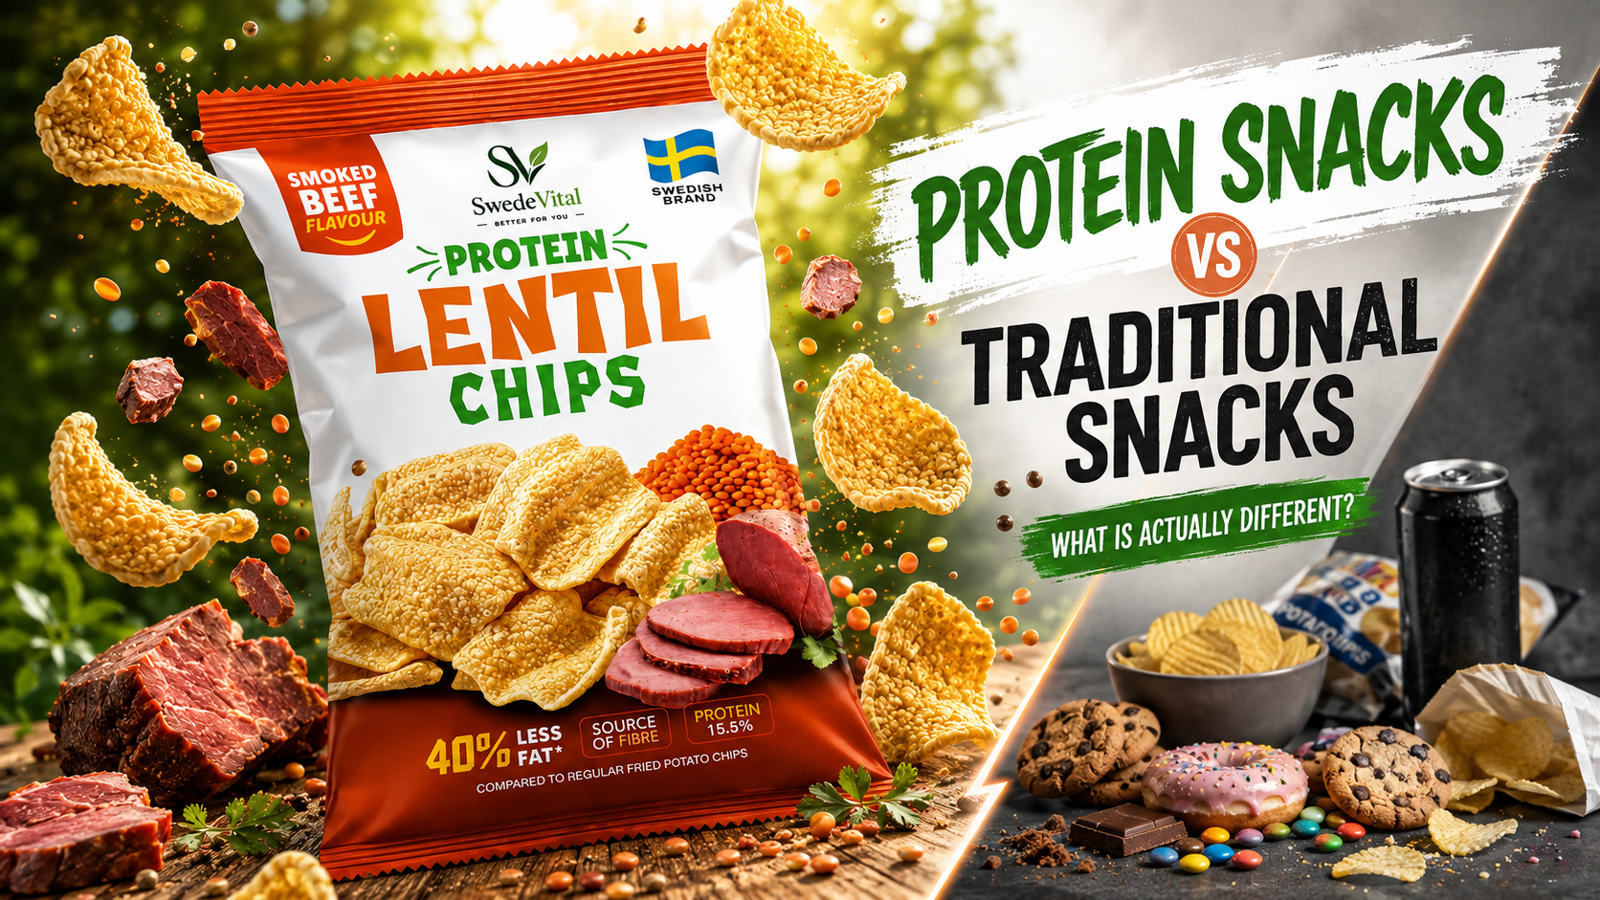
For a category manager or distributor, launching a protein snack into retail is a decision to allocate shelf space, working capital and merchandising attention to a product that must earn its place against incumbents. The protein category itself is mature: shoppers have bought protein powder and ready-to-drink shakes for years, and that familiarity has done the hard work of normalising protein as an everyday purchase. Growth has now migrated into snacking — portable, better-for-you formats such as protein lentil chips, protein bars and protein bites that fit into ordinary eating occasions rather than a gym routine.
Entering that segment successfully means answering a buyer's core question before they have to ask it: will this product sell fast enough, at an acceptable margin, to justify the space it occupies? Everything that follows is a method for producing a credible, evidence-based answer to exactly that.
Why the first store matters more than the first order
New suppliers tend to celebrate the first purchase order. Experienced buyers watch something else entirely: rate of sale. A single store, chosen well and merchandised properly, tells you more about a product's real potential than a large opening order spread thinly across many locations where nobody is paying attention. The first store is where you learn whether shoppers pick the product up unprompted, whether they come back, and whether the price point survives contact with the shelf.
Run the pilot long enough to see repeat purchase, not just novelty. A short trial captures curiosity; a longer window captures habit. During that period, isolate as many variables as you can — consistent facings, a stable shelf position, and a clear read on what the product is displacing. If a protein snack only sells when it is on promotion, you have learned something important before scaling the mistake.
Choosing the right first retail partner
The instinct is to chase the largest possible retailer first. Resist it. A national listing that fails quietly on a bottom shelf can poison a product's reputation with the buying community for a long time. A better first partner is one where you can influence execution and observe results closely.
- Shopper fit — the store's customers should already be buying adjacent products: better-for-you snacks, functional foods, sports nutrition or premium grocery.
- Merchandising control — independents, forward-thinking regional chains and specialist retailers often allow better placement and faster feedback than a large multiple.
- Data access — a partner willing to share EPOS or sell-through figures is worth more than one offering more doors but no numbers.
- Category authority — a respected store's willingness to stock you becomes social proof in later conversations with bigger buyers.
The goal at this stage is not volume. It is a clean, observable, repeatable result you can point to.
Pricing, margin and MOQ trade-offs
Pricing is where many protein snack market entries quietly go wrong. Retail buyers work backwards from a shelf price the shopper will accept, subtract the margin the category requires, and arrive at the cost price they can pay. If your landed cost does not leave room for the retailer's expected margin at a believable shelf price, no amount of product quality will fix the maths.
Rather than fixating on a single number, map the trade-offs explicitly:
- Shelf price vs. velocity — a premium price protects margin but slows rate of sale; the right point is the one that keeps both healthy.
- Introductory terms vs. anchoring — deep launch discounts can buy a listing but train shoppers and buyers to expect a lower price permanently.
- Minimum order quantity vs. risk — a lower MOQ lowers a first buyer's exposure and makes yes easier; a higher MOQ improves your unit economics. Early on, reducing the buyer's risk usually beats optimising your own.
- Case size vs. shelf life — case configuration should match a realistic weekly rate of sale so stock turns before it ages.
Be transparent about cost drivers — clean-label ingredients, plant-based protein sources and smaller production runs all carry cost — but never quote figures you cannot stand behind. Buyers remember a supplier who over-promised on margin far longer than one who was candid.
From shelf to sell-through: making the pilot count
A listing is not a launch. What turns a first store into a scalable case is what happens in the weeks after the product lands. Treat merchandising as part of the product, not an afterthought.
Position and visibility
Eye-level placement, a coherent block of facings and proximity to the products your shopper already buys will move more units than any single design change. Where a store permits it, a small amount of secondary placement — a shipper or a spot near the checkout — can reveal whether the product travels on impulse.
Communicate the reason to buy in seconds
Shoppers decide at the shelf in moments. The pack and shelf edge should answer, without effort, what the product is, why it is a better-for-you choice, and who it is for. For functional or protein claims, keep language accurate and evidence-led — describe what a product contains rather than promising outcomes it cannot guarantee.
Measure what actually predicts scale
- Rate of sale per store per week — the single most portable metric across a growing footprint.
- Repeat purchase — evidence the product builds a habit, not just trial.
- Basket behaviour — whether it is incremental or simply cannibalising an existing line.
- Waste and returns — a signal that case size, forecasting or shelf life needs attention before it scales.
Scaling to wider distribution
Once a pilot shows real velocity and repeat purchase, a protein snack market entry moves from proving demand to engineering reach. This is the stage where channel structure starts to matter as much as the product.
Direct-to-retail vs. distributor
Selling directly to a handful of retailers keeps margin and control in your hands and is well suited to the pilot phase. But direct relationships do not scale cheaply — every new region multiplies logistics, credit risk and account management. A wholesaler or distributor buys reach, existing buyer relationships and route-to-market efficiency in exchange for margin. The right moment to bring one in is when the cost and complexity of serving stores directly starts to outweigh the margin you keep by doing so.
Regional before national
Expanding within one region before reaching for a national listing lets you stress-test supply, replenishment and forecasting at manageable scale. A national listing demands consistent availability from day one; failing to supply it is far more damaging than never winning it. Grow the footprint at the pace your operations can genuinely support.
Private label as a parallel route
For manufacturers, a private-label or contract-manufacturing programme can run alongside a branded push. It trades brand visibility for volume and a retailer partner with a direct stake in the product's success. For a supplier with strong production capability across formats — protein chips, bites and bars, or a functional-wellness line — private label can be the faster route to scale, provided it does not undercut the branded proposition you are still building.
A protein snack market entry checklist
Before approaching a first retailer, work through this list — and be honest where an answer is missing rather than assuming it.
- Positioning — can you state in one sentence what the snack is, who it is for, and why it is a better choice?
- Shopper fit — have you identified the specific shopper and the products your snack sits beside?
- Price architecture — does your cost price leave a believable shelf price and the retailer's expected margin intact?
- Supply reliability — can you fulfil reorders consistently, with realistic lead times and shelf life?
- Compliance and labelling — do claims, allergens and nutrition information meet the requirements of every market you intend to sell in?
- Measurement plan — have you agreed how sell-through and repeat purchase will be tracked with the first partner?
- Scale readiness — do you know the trigger point at which you move from direct supply to a distributor?
Common mistakes that stall a launch
Most failed entries share a small set of avoidable errors. Chasing too many doors before proving velocity spreads attention and stock too thin to learn anything. Buying a listing with unsustainable launch discounts anchors both shopper and buyer expectations at a price that erodes margin later. Neglecting merchandising treats a listing as the finish line when it is only the start. And over-claiming — on health benefits or on the margin a retailer can expect — damages the trust that wider distribution is built on. A disciplined, evidence-led entry avoids all four by design.
Handled this way, a market entry becomes a repeatable engine rather than a gamble: prove it small, read the data honestly, and let genuine sell-through — not persuasion — open the next set of doors.
Vanliga frågor
How is a protein snack different from protein powder for a retailer?
Protein powder is a mature, planned purchase bought mainly by fitness-focused shoppers, usually in larger formats with slower shelf turnover. Protein snacks such as chips, bites and bars are portable, single-serve, impulse-friendly formats that reach a much broader everyday shopper. For a buyer that means different shelf locations, faster potential rate of sale and a wider target audience than the sports-nutrition aisle alone.
How many stores should a new protein snack start in?
Start small enough to observe and influence execution closely, often a single store or a tight cluster where you can control facings and access sell-through data. The aim of the pilot is clean, repeatable evidence of velocity and repeat purchase, not opening volume. Expand only once that data justifies the risk and cost of more doors.
How long should a protein snack pilot run before scaling?
Run it long enough to see repeat purchase rather than first-week novelty, so you can distinguish genuine habit from curiosity. The exact window depends on the store's footfall and the product's purchase cycle, but scaling before you have seen shoppers return risks multiplying a result that was never real demand in the first place.
Should a protein snack go direct to retailers or through a distributor?
Sell direct during the pilot to keep margin, control and close feedback. Move to a wholesaler or distributor when the logistics, credit risk and account management of serving stores directly start to outweigh the margin you keep by doing it yourself. Distributors buy reach and existing buyer relationships in exchange for margin.
What data should a buyer collect during a protein snack trial?
Track rate of sale per store per week, repeat purchase, whether the product is incremental to the basket or cannibalising an existing line, and any waste or returns. These metrics travel well across a growing footprint and predict whether a listing will scale far more reliably than a single opening order or anecdotal shopper feedback.
How should pricing be set for a protein snack market entry?
Work backwards from a shelf price shoppers will accept, subtract the margin the category expects, and confirm your landed cost still fits underneath. Avoid deep launch discounts that anchor expectations low, and be candid about cost drivers such as clean-label ingredients and smaller runs rather than quoting margins or figures you cannot sustain.